The winding road from financial access to financial outcomes
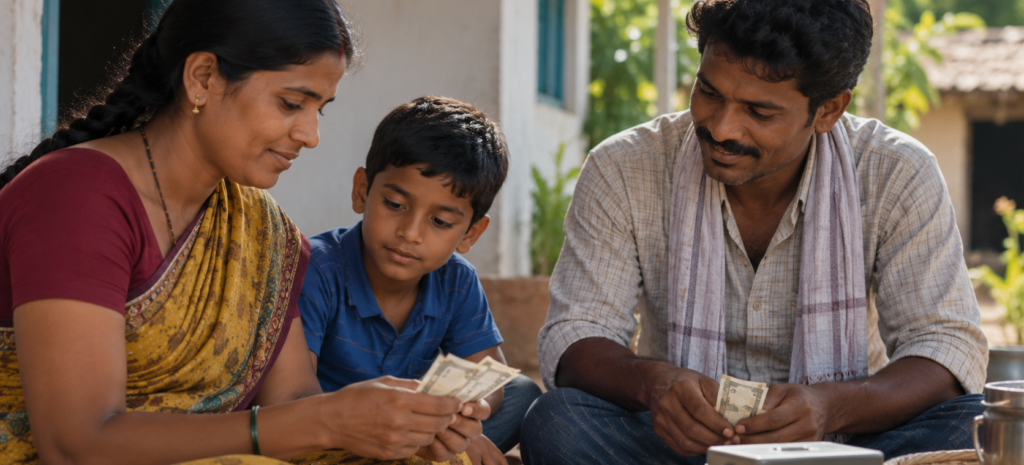
India’s financial inclusion numbers are often presented as a policy success story. The Reserve Bank of India’s (RBI) Financial Inclusion Index increased from 64.2 in 2024 to 67 in 2025. Bank accounts, credit, digital payments, and insurance products have all scaled significantly over the past decade. By nearly every access metric that is traditionally tracked, the story looks like unambiguous progress.
Impact of information disclosure on consumer behaviour: The case of high-risk bonds
Impact of information disclosure on consumer behaviour: The case of high-risk bonds
Covid-19 and debt moratorium conundrum: The case of microfinance
Given the extent of liquidity shock caused by Covid-19, the Reserve Bank of India enabled all lending institutions to provide their borrowers with a repayment moratorium on term loans until 31 August 2020.
Barriers to basic banking in India
The Indian government is promoting the Jan Dhan Yojana, Aadhaar and mobile banking – or the “JAM trinity” — as the pathway to financial inclusion. But are banks capable or even willing take on their role in this ambitious agenda? Based on a field study in Chennai, this column highlights the range of costs and constraints imposed by banks on customers attempting to enter the formal financial sector.
Barriers to basic banking in India
The Indian government is promoting the Jan Dhan Yojana, Aadhaar and mobile banking – or the “JAM trinity” — as the pathway to financial inclusion. But are banks capable or even willing take on their role in this ambitious agenda? Based on a field study in Chennai, this column highlights the range of costs and constraints imposed by banks on customers attempting to enter the formal financial sector.