Cyber resilience in banking sector
The Reserve Bank of India has its task cut out. Real time information sharing has to be operationalised
The winding road from financial access to financial outcomes
India’s financial inclusion numbers are often presented as a policy success story. The Reserve Bank of India’s (RBI) Financial Inclusion Index increased from 64.2 in 2024 to 67 in 2025. Bank accounts, credit, digital payments, and insurance products have all scaled significantly over the past decade. By nearly every access metric that is traditionally tracked, the story looks like unambiguous progress.
The big truth about nano-enterprises that dominate MSME segment
MSME segment is mammoth and has very distinct and crucial subcategories. Responding to this heterogeneity can spur momentum across the entire sector
Remedies for digital payment frauds
Static safeguards, targeting discrete acts of fraud, will only spur fraudsters to probe other vulnerabilities
Microfinance needs reform more than credit backstops if India wants to avert another crisis in this sector
Liquidity support by the Centre may offer symptomatic relief, but India’s microfinance sector needs a structural recast. Without reforms to address recurring cycles of over-lending and loan stress, another credit guarantee package will only postpone the next crisis in this fragile sector.
Responsible AI in digital lending
Fairness, explainability and human-in-the-loop principle are vital elements of Responsible AI
Responsible AI means good business for all
When AI-driven decisions are fair, respect privacy and are not opaque, they foster customer confidence
How to develop trustworthy AI in digital lending
Establishing principle-level guidance on operationalising Responsible AI would induce clarity and confidence
Need a more flexible AePS environment
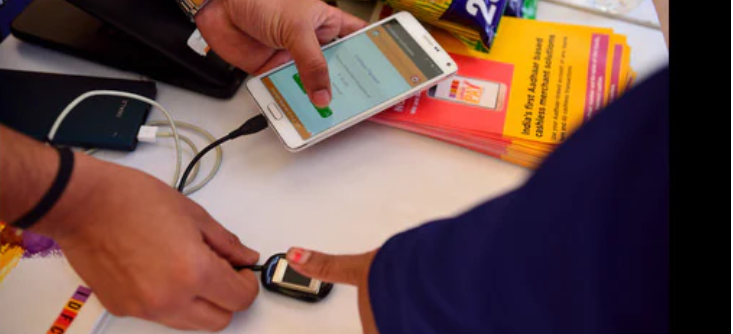
While the Aadhaar Enabled Payment System (AePS) has emerged as the foundational technology enabling cash-in cash-out (CICO) across the country, efforts by bad actors to defraud banking customers through it continue to be a pressing concern
UPI’s democratised cashless payments but not grievance redressal
Medium-to-low digital proficiency users experience anxiety when they have to use in-app mechanisms to deal with problems. It has got to do with designs that do not account for user proficiency and expectations. A few changes could uplift the experience for all users