Our Response to RBI Draft Directions for Comments on Due Diligence of AEPS Touchpoint Operators
In response to concerns of fraud perpetrated through the Aadhaar enabled Payments System (AePS), the RBI has issued (draft) directions to all banks and to the NPCI for onboarding and ongoing due diligence of AePS touchpoint operators.
Assessing the Performance of PMJJBY and PMSBY: A Systems-Level Approach
The objective of this deck is to summarise learnings from fieldwork conducted in Rajasthan and Gujarat towards (i) building evidence on the customer protection issues in the sale and servicing of the two insurance schemes and (ii) bringing to the forefront the structural issues on the supply-side that are holding back Financial Service Providers (FSPs) from offering high-quality service in the context of these two schemes
Building an Effective UPI In-App GRM for India’s Consumers
In this study, we focus on whether consumers use the grievance mechanisms provided in UPI apps in smartphones, and whether those mechanisms make for an easily navigable grievance redress journey ending in satisfactory resolution.
Learnings from Action Research
In this paper, we take a look back at 30 months of action research work and reflect on the process, the hurdles overcome, and the lessons learned. Unlike our usual publications, this one is a meta-reflection on the method of action research. We hope it will be useful for other organizations like ours that are doing this kind of work and to funders who fund it.
Agriculture Finance in India: A Landscape Review of Challenges & Opportunities
How can finance be designed and structured for agriculture, farmers, agricultural households, agrarian communities and the larger economy so as to ensure economic equity, social well-being, and environmental sustainability?
A High-Frequency Cashflow Analysis of Low-Income Households in India
This paper aims to document the unique characteristics of the financial lives of low-income households in India. It focuses on the intra-year fluctuations in income that are faced by these households owing to the precarity of their occupations.
Rethinking Financial Management for Low income Households
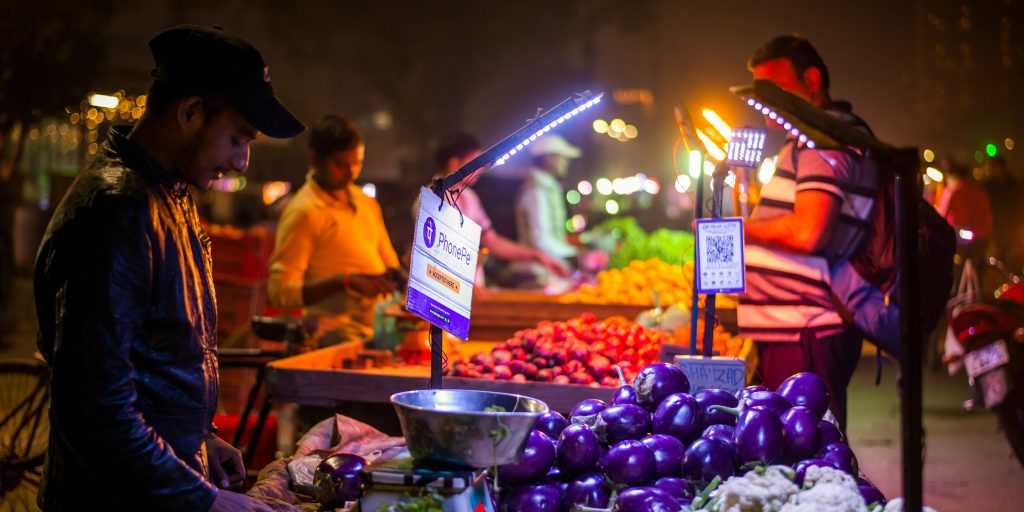
The paper starts by revisiting existing literature on the financial lives of LIHs that shows that they manage their finances in a rather sophisticated manner. This can be traced to the radical uncertainty they face, which includes a “triple whammy” of income problems and expenditure shocks that are frequent and unique to their circumstances.
The Problem with Hospicash
How can we provide meaningful financial protection to people who are currently not served by health insurance markets (public or private)? This is the issue Bindu and her team at Dvara Health Finance have been working on for the past couple of years.
Curbing Scams in Unified Payments Interface
The white paper discusses a set of solutions for the ecosystem of actors to consider in tackling and curbing the illegitimate activity of scamsters and other fraudulent actors over the very popular Unified Payments Interface (UPI) of India.
Assessing the Borrower-Level Impact of the Insolvency and Bankruptcy Code: A Study of the Fresh Start Process
The 2016 Insolvency and Bankruptcy Code (IBC) is a landmark legislation with the potential to impact every borrower. This paper focuses on Part III of the IBC, which deals with natural persons, proprietorships, and personal guarantors for corporate debt. Through the paper, we attempt to estimate the potential consequences of the Fresh Start Process (FSP) defined under this Part. The IBC lays out economic criteria that can qualify (or disqualify) an applicant for FSP. Under FSP, a borrower must be asset-lite, have a low income, and hold minimal outstanding debt to qualify. These thresholds determine the applicability of the process once the IBC is fully notified. Thus, empirical estimates regarding the effects of the provisions on the Indian credit market are crucial to deciphering the impact of the IBC, more specifically, the FSP.